Author Note: Even if the semester is already underway, it can still be worthwhile to review these steps and clear up any financial details that may not have been addressed before move-in.
The final weeks before college have a way of filling up fast with forms, shopping, move-in plans, and last-minute logistics. A short financial review can help move a few important decisions from assumed to agreed upon before the semester begins.
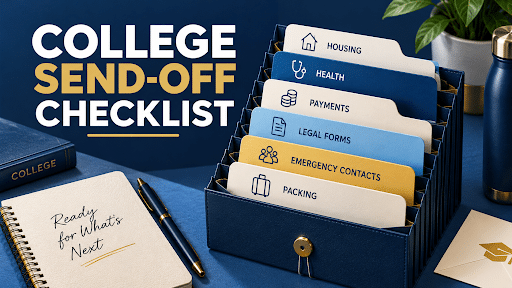
The most useful checklist focuses on the systems that change as your child starts living more independently. Work through these four steps so everyone knows how things are supposed to work.
Step #1) Get Clear on How College Costs Will Actually Be Paid
Start by mapping out what each source of money is intended to cover and who will handle each type of expense. Scholarships, 529 accounts used for college expenses, family cash flow, and student money may all play different roles, so both parent and student should understand the basic funding plan before the first bill arrives.
Common qualified 529 expenses can include:
Tuition and required fees associated with enrollment or attendance.
Books, supplies, and equipment required for coursework.
Computers, certain software, and internet access used while the student is enrolled.
Room and board for students who meet the applicable enrollment requirements, subject to certain limits.
Certain special needs services related to enrollment or attendance.
Please Note: Make sure you understand the full range of qualified 529 expenses.1 Some expenses come with additional requirements or limits, particularly room and board and technology-related costs. Keep receipts and school documentation with your records, and check an expense before withdrawing money if you are unsure whether it qualifies.
Agree on the Money Flow Before the First Bill Arrives
Decide where the money starts and where it goes. A common setup is for the parent or 529 account owner to handle tuition and other major qualified costs, either by sending 529 money directly to the school or by paying an eligible expense and coordinating reimbursement, while scholarships or other aid are applied separately.
For books, equipment, housing, and other eligible costs paid outside the school’s billing system, decide whether the parent or student will make the purchase and how reimbursement will work. Your child should know when to send a receipt, who initiates the 529 withdrawal, and that money received for a qualified expense is earmarked for that purpose rather than becoming general spending money.
Keep ordinary personal spending on a separate track. You might send a set amount to your student’s checking account or use Zelle or Venmo for agreed-upon expenses, while your child covers other purchases from earnings or their own savings. The exact arrangement matters less than clearly defining what the family pays, what the student pays, and which expenses require a conversation first.
Step #2) Give Your Insurance Coverage a College Checkup
College can change where your child receives medical care, where a vehicle is kept, and how their belongings are covered. Review the policies you already have before move-in so you know what follows your student to school and whether anything needs to be changed.
|
Coverage |
What to Review |
What to Confirm |
|---|---|---|
|
Health insurance |
Verify dependent coverage extends until age 26 on the family plan, campus provider network, nearby urgent care/hospitals, prescriptions, and student health plan offerings. |
Student has insurance cards/apps, knows where to access covered care, and understands whether family or school coverage applies. |
|
Auto insurance |
Notify insurer if vehicle goes to campus or stays home. Review impacts of garaging location, mileage, and student-away status. |
Insurer location/usage details are accurate and eligible student discounts are applied. |
|
Dorm or renters coverage |
Check homeowners/renters coverage limits and deductibles for dorm stay. Determine if a separate policy is needed off-campus. |
Personal belongings (laptops, bikes, electronics) and liability are adequately covered for the living setup. |
Step #3) Double-Check These Documents Once Your Child Turns 18
Turning 18 changes the parent’s legal ability to automatically receive certain information or act for a child, even when the child is still financially dependent. Before college, discuss what access makes sense for your family and complete any documents you decide are appropriate rather than waiting until an emergency to figure out what is missing.
The exact forms and requirements can vary by school, provider, and state, but these are the main documents to review:
FERPA release or consent form: Allows your student to authorize the college to disclose specified education records to you. Use the school’s own process and decide together what information, if any, will be shared.
HIPAA authorization: Gives specified health care providers permission to share certain medical information with the people your child names. It addresses access to information rather than automatically giving someone authority to make medical decisions.
Health care power of attorney or advance directive: Allows your adult child to designate someone to make health care decisions if they become unable to make those decisions themselves. The appropriate document and requirements depend on state law.
Durable financial power of attorney: Can give a designated person authority to handle specified financial or legal matters if needed. Families considering one should discuss the appropriate scope with an attorney rather than treating it as a routine blanket authorization.
Step #4) Look at What This Transition Changes for Your Own Finances
College can gradually reshape the household budget. Some costs at home may decline while tuition, travel, continued support, or other college expenses take their place, so update your cash flow based on what your family will actually be paying over the next several years.
Think ahead about what happens when those costs eventually decline as well. Money that once went toward college or other child-related expenses could later be redirected toward retirement contributions, cash reserves, debt reduction, travel, or another priority instead of quietly becoming additional lifestyle spending.
For parents approaching the full empty nester stage, the college send-off can also mark the beginning of a larger financial transition. Your child’s growing independence creates a natural point to revisit what you want your own finances to support in the years ahead.
College Send-Off FAQs
1. What financial things should parents review before a child leaves for college?
Start with exactly how college costs will be funded and who will handle tuition, 529 withdrawals, and everyday expenses. Then review insurance coverage, adult-child documents and permissions, and how the new expenses affect your own household plan.
2. Can a 529 plan pay for college housing?
Room and board can qualify in certain circumstances when the student meets the applicable enrollment requirements. Limits can depend on the school’s published room-and-board allowance or the amount charged for certain school-owned housing, so verify the eligible amount before taking a distribution.
3. Does my child need dorm insurance when they go to college?
Not necessarily. A parent’s homeowners or renters policy may extend some coverage to belongings in a dorm, while an off-campus apartment may call for a separate renters policy. Review the deductible, property limits, personal liability coverage, and any limits that apply to higher-value items such as laptops or bikes.
4. What documents should parents have once a college student turns 18?
Common documents to review include the school’s FERPA authorization process, a HIPAA authorization, and potentially a health care or financial power of attorney. Which documents make sense depends on the family’s preferences and applicable state requirements.
5. How much spending money should I give my college student each month?
First define which expenses your student is expected to handle since housing, meal plans, transportation, and family support can vary substantially. Set an initial amount around those responsibilities and your budget, then revisit it after a month or two once you have real spending information.
Get Your Family Ready for the College Send-Off
A thoughtful college send-off review can help you settle the financial details that are most likely to matter once your child begins living more independently. Clarifying how college costs will be paid, reviewing insurance, putting the right documents in place, and accounting for changes to your own cash flow can make the transition more organized for the whole family.
A financial advisor can help connect these decisions to the rest of your plan. That may include coordinating 529 withdrawals with other funding sources, reviewing how college expenses affect cash flow and retirement contributions, and helping you think through how your priorities may shift as your child becomes more independent.
At Crafted Finance, we would love to help you work through this transition and see how college fits into the bigger picture of your family’s finances. If you would like a second set of eyes on your plan, you can schedule a complimentary call with us using the button below.